The Pilot’s Checklist: Why Even Experts Need a Short List Before They Act

The Cheapest Money in Town: Why What a Bank Pays for Its Money Decides How Good the Bank Can Be
October 13, 2026
On the morning of 30 October 1935, a gleaming new aeroplane rolled down a runway at Wright Field, an air force base in Dayton, Ohio. It was the Boeing Model 299, a bomber with four engines, and it was there to win a contest. The United States Army wanted a new long-range bomber. This machine had already flown nonstop from Seattle to Dayton, about 2,100 miles, faster than the judges had ever seen. Its crew were among the best pilots in the country. The plane lifted off, climbed to about 300 feet, stalled, turned over and burst into flames. Two of the five men on board died of their injuries.
The investigators searched for a broken part and found none. The engines, the propellers, the structure and the design were all cleared. The board found that the control which tilts the nose up and down had been left locked. The aeroplane was so much more complicated than the ones before it that even the best pilot could miss a single step in the rush before takeoff.
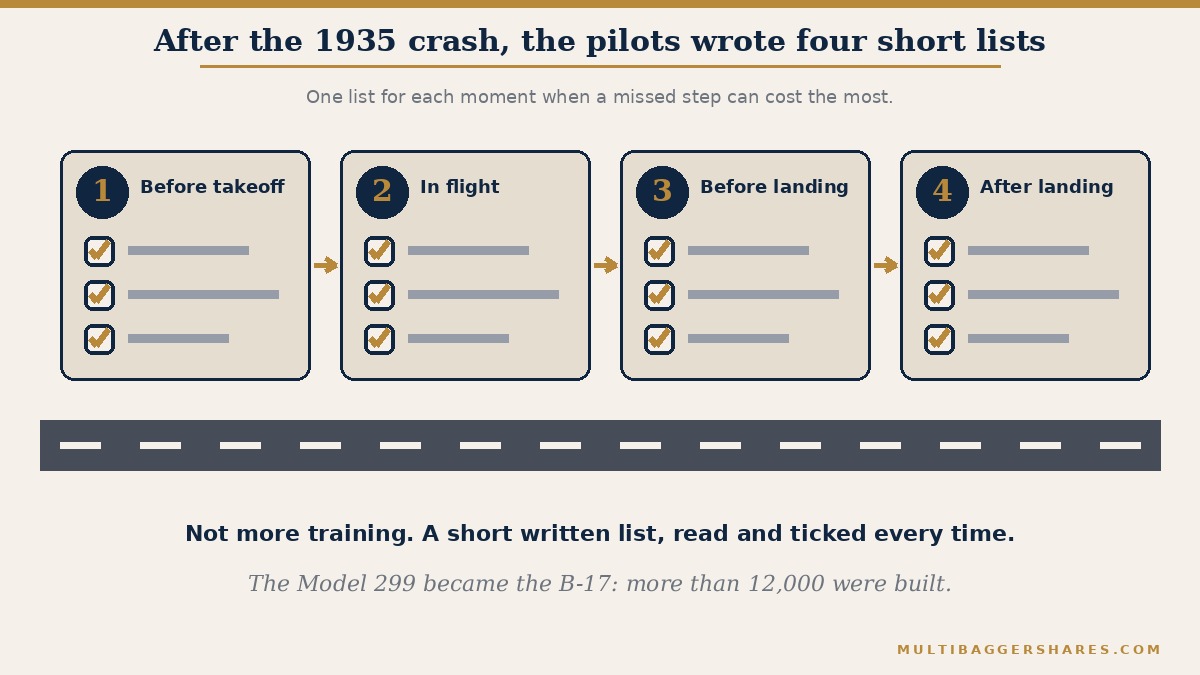
The Army did not send its pilots back to school. It did something far plainer. The pilots wrote a short checklist (a written list of steps that you tick off one by one) for four moments: before takeoff, in flight, before landing, and after landing. The Model 299 went on to become the B-17, and more than twelve thousand of them were built. The lesson was not that the pilots were weak. It was that even the strongest memory can fail when a job is complex and the clock is running.
That lesson matters to anyone who makes decisions with real money at stake, including a long-term investor. Let us see why.
What it really means
A checklist is a short written list of the steps that must not be missed. It is not a manual. It does not teach you how to fly or how to judge a business. It does one small job only. It catches the step you forgot.
There are two kinds of mistake. In the first kind, we do not know something. The cure for that is learning. In the second kind, we know exactly what to do, but in the heat of the moment we skip it. Think of your mother getting ready for a family wedding. She is a brilliant organiser. She has done it many times. Yet she still writes a list on the back of an old envelope, because with twelve things happening at once even a brilliant mind forgets the haldi, the garlands or the sweet boxes. The list does not make her smarter. It makes her reliable.
Atul Gawande, an American surgeon and writer, made this idea famous in his 2009 book The Checklist Manifesto. His argument was simple. The amount that we know has grown beyond what any one person can carry reliably in their head. Doctors, pilots and builders all now work with so many details that the biggest risk is no longer ignorance. It is forgetting something we already know.
Notice something curious. Experts need checklists more than beginners do. A beginner is careful because every step is new. An expert has done the job a thousand times, so the hands move on their own, and that is exactly when a step can slip by unnoticed. The kirana shopkeeper who has locked his shutter every night for thirty years is the one who one night forgets to switch off the gas. Habit is a great helper, but it is also a quiet thief of attention.
Why it works
The first reason is that memory is weakest exactly when we need it most. When we are excited, hurried or worried, the mind narrows. It holds on to the big, interesting parts of the job and lets the dull parts fall away. A list is not excited, hurried or worried. It simply asks the next question, every time, in the same order.
The second reason is that a list is written when we are calm and used when we are not. The pilots who wrote the first checklists were sitting quietly with the lessons of a crash fresh in front of them. They did not have to be clever at the moment of takeoff. They only had to read what their calmer selves had written down. For an investor this matters a great deal. The moment a business story excites you is the worst moment to decide which questions are important. Better to settle that long before, on a quiet Sunday.
The third reason is that a list takes the ego out of the room. When a checklist says check the debt, nobody feels insulted. The senior person and the junior person tick the same boxes. A rule that applies to everyone is easy to follow. A rule that is only for beginners is easy to ignore.
The fourth reason is that a list gets better over time. Every real mistake can add one line, and every useless line can be removed. Aeroplane checklists grew in just this way, one lesson at a time. After a while, the list holds the hard-earned wisdom of everyone who has made the mistake before you.
One honest warning belongs here. A checklist is not a substitute for thinking. It will not tell you whether a business is wonderful. It only makes sure that you have looked at the things that matter before you decide. A list that grows to forty items soon becomes a chore, and people begin to tick boxes without reading them. The best lists are short on purpose.
A real example or two
Our first example comes from a hospital, far from any stock market. Many patients in intensive care units (the wards for the sickest patients) need a central line. This is a thin tube placed into a large vein to give medicines. If germs travel down the tube into the blood, the patient can become gravely ill. These infections were common, and every doctor knew the basic steps to prevent them.
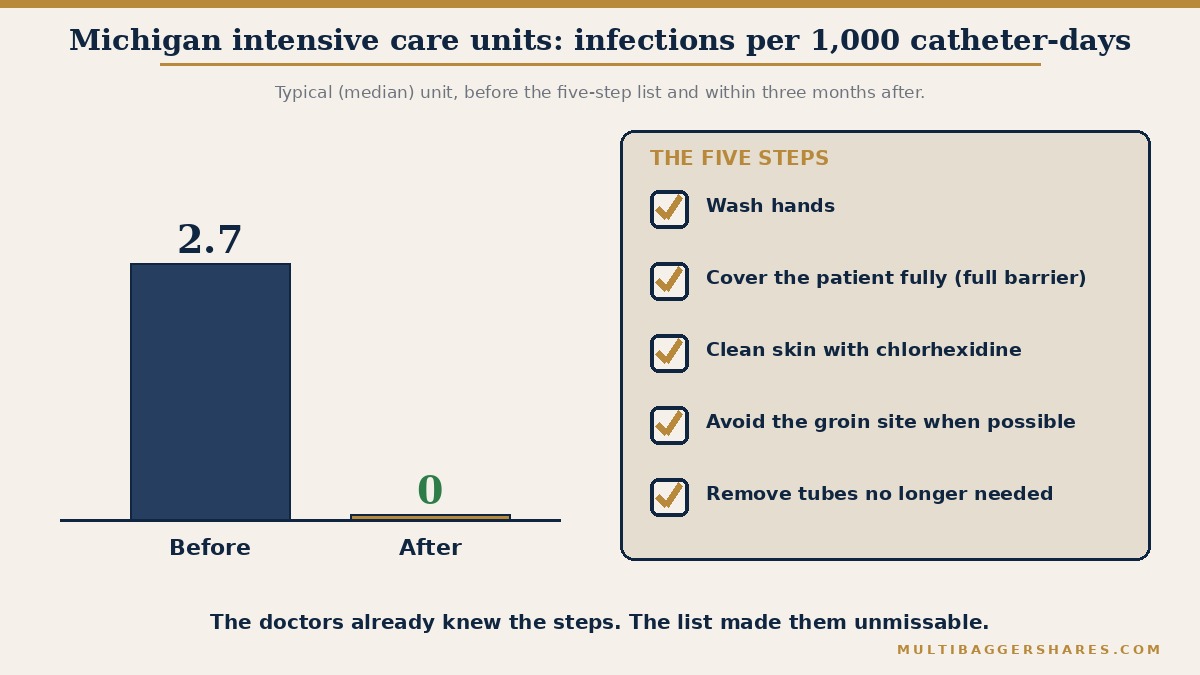
A team led by Dr Peter Pronovost of Johns Hopkins University worked with more than a hundred intensive care units across the state of Michigan. They asked the staff to follow five plain steps every time a central line was placed: wash hands, use full-barrier precautions (cover the patient from head to toe, as in an operation), clean the skin with an antiseptic called chlorhexidine, avoid the groin as the insertion site when possible, and remove tubes that are no longer needed. The project also gave units a cart with all supplies in one place and fed back their infection numbers every month. But the heart of it was a short list that someone ticked each time.
The result was reported in the New England Journal of Medicine in 2006. Before the project, the typical unit had 2.7 infections for every 1,000 catheter-days (a catheter-day is one day that one patient has one line in place). Within three months, the typical unit had zero, and the improvement held for the long follow-up that came after. Nothing new had been discovered. The doctors had always known the steps. What changed was that the steps were now written down and checked.
Our second example is imaginary, and it is about money. Picture an investor called Anil. At a wedding, a friend tells him a gripping story about a small company that is growing very fast. Anil goes home excited. He reads the company’s website, loves the story and checks the growth. He does not check the one dull page that shows how much the company has borrowed. Two years later, a slow year arrives, the lenders ask for their money, and the story ends badly. Anil was not a foolish man. He simply skipped a step he knew was important, because the exciting part of the job filled his whole mind.
A checklist would not have told Anil which business to pick. It would only have said, in a calm voice, have you looked at the debt? That single question, asked at the right moment, is often all that stands between a good decision and a painful one.
We name no company here and we are not saying anything should be bought or sold. The point is the habit of mind. The same habit saved patients in Michigan and, in a different way, made a famous bomber safe to fly.
How you can use it
You can build your own checklist in an afternoon. Keep it to about five questions, written in plain words. Here is a starting card to think about. Change it to suit you.
First, can I say in two sentences what this business sells and who pays for it? If you cannot, the business may lie outside your circle of competence (the zone of things you truly understand). That is a perfectly good reason to move on.
Second, in most of the last ten years, did the profit show up as real cash? Profit on paper can be promised and still not arrive. Cash flow (the money that actually comes into the till) is the proof that the profit was real.
Third, could the business survive a bad year without begging its lenders for time? Debt (money borrowed that must be repaid on a fixed date) is the item that most often turns a slow year into a crisis. This is Anil’s missing question.
Fourth, do the people in charge talk about bad news as plainly as good news, and do they have a real stake of their own in the business? Honest and capable managers are rare. You can learn a lot from how they write about a year that went wrong.
Fifth, what is the one thing that would prove me wrong, and have I written it down? This question is the hardest, and perhaps the most useful. It forces you to think about how you could be mistaken before you fall in love with your own idea.
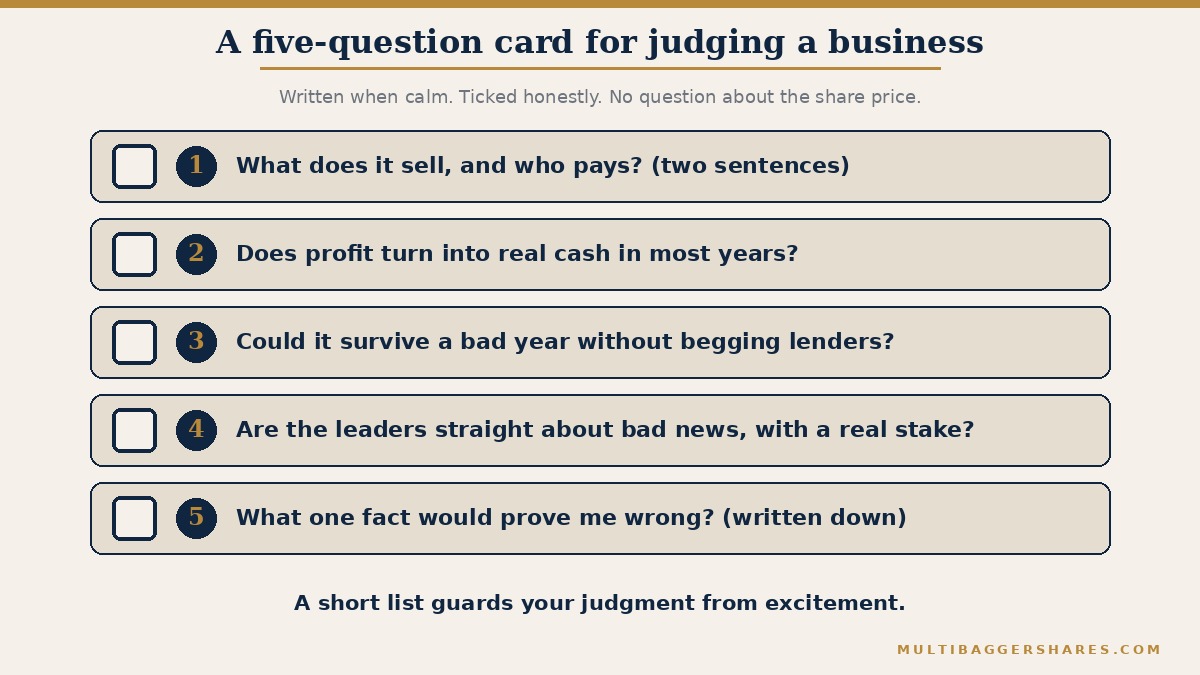
Notice that none of the five questions asks about the share price. That is deliberate. These questions are about the quality of the business, and quality is the part of the job that a calm checklist can protect. Whether you answer yes, no or not sure, write it down. A no is not a failure. It is information you would not have had if the excitement had been allowed to decide.
A few rules will help. Write the list when you are calm, not when a story has just excited you. Keep it short, so you will actually read it. Tick it honestly, and never tick a box you have not really checked. After any mistake, ask which question would have caught it, and add that question. And remember that the list serves your judgment. It does not replace it.
Lastly, be patient with yourself. In 1935 the best pilots in the country needed a list. Nobody is too experienced, too clever or too busy to benefit from one. The wise do not trust their memory. They trust their routine.
This article is for education only. It does not tell you what to do with any particular investment.
Key takeaways
- A checklist is a short written list that catches the step you already know but forgot.
- Experts need checklists most, because habit makes skipping a step easy and invisible.
- The first pilot’s checklist after the 1935 Model 299 crash, and the five-step list in Michigan intensive care units, both worked by making known steps unmissable.
- Write your list when you are calm, keep it to about five questions, and ask about business quality, not the share price.
- A checklist protects your judgment from excitement. It never replaces it.
— Manish Goel · multibaggershares.com
Manish Goel is a Chartered Accountant and Principal Officer of Multibagger Securities Research & Advisory Pvt. Ltd. (MSRAPL), a SEBI-registered Investment Adviser, Registration No. INA100007736. This content is published by MSRAPL for education only and is not personalized investment advice.
Disclaimer: This article is published by multibaggershares.com for education and general information only. It is not investment advice, investment research, or a recommendation to buy, sell or hold any security. Any companies named are discussed only as illustrative examples. Markets carry risk; please do your own research or consult a qualified professional before making any investment decision. |